CNG vs Bio-CNG vs EV: India’s 2030 Green Mobility Race Decoded
An authoritative segment-by-segment analysis of India’s green mobility race by 2030. Compare CNG, Bio-CNG, and EVs on real CapEx, apartment charging, and fuel TCO.
Projected 50% gas-powered vs 30% EV across total vehicle kilometers
Vs ₹4.5–6.0 Lakh battery premium for entry-level electric hatchbacks
Expanding to 15,000+ highway & urban dispensers by 2030
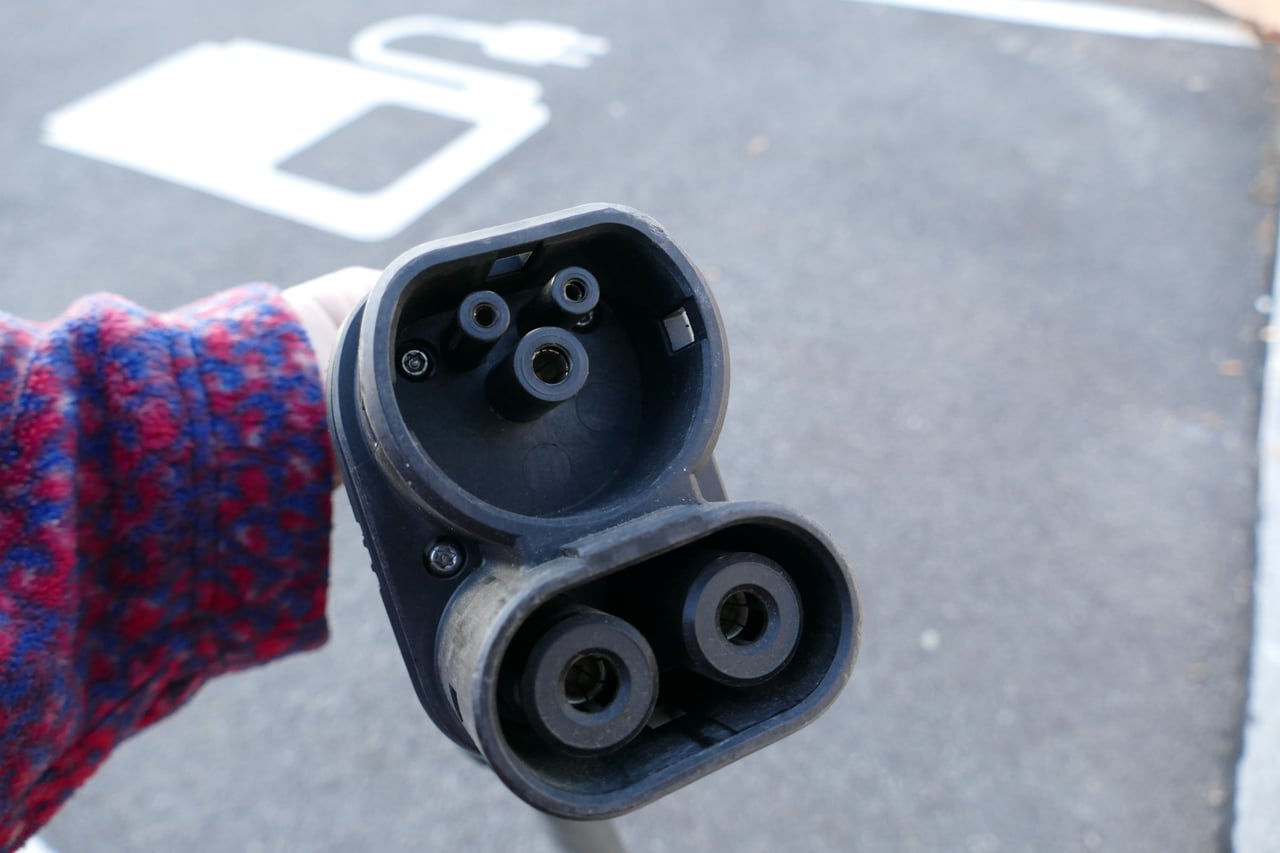
Car owners in multi-story apartments without home charging access
For the past five years, the public conversation around clean mobility in India has been dominated by a binary debate: Internal Combustion vs. Electric Vehicles. Social media threads, venture capital pitches, and automotive expos frequently proclaim that the transition will be immediate, total, and purely electric.
Yet, step outside into the reality of Indian roads, and a very different picture emerges.
In 2025, over 21% of all passenger cars sold in India are factory-fitted CNG vehicles—a record high recorded by the Society of Indian Automobile Manufacturers (SIAM). At the same time, passenger electric cars (EVs) hover around 2.4% of retail deliveries, despite massive government incentives under FAME and state subsidies. Meanwhile, India’s Bio-CNG (Compressed Bio-Gas / CBG) infrastructure is expanding under the central SATAT initiative, transforming urban municipal solid waste and agricultural residue into drop-in renewable methane.
This raises the critical question for prospective car buyers, commercial fleet managers, and policy makers: Which fuel will actually rule India’s green mobility race by 2030?
The answer is not a simplistic single-winner contest. India’s distinctive income distribution, housing architecture, and freight economics are forging a pragmatic, multi-fuel equilibrium—one where clean gas molecules and high-voltage electrons each dominate the specific domains where they make economic and physical sense.
🔬 The Three Contenders: Physical Realities & Economic Profiles
To evaluate who wins by 2030, we must first demystify the three clean powertrains competing for Indian asphalt:

1. Fossil Compressed Natural Gas (CNG)
- Chemical Profile: 85–95% Methane ($CH_4$), compressed at 200–250 bar pressure.
- Infrastructure Footprint: Over 8,340 retail dispensing stations nationwide in 2025, backed by an expanding 33,500 km national steel pipeline grid authorized by the Petroleum and Natural Gas Regulatory Board (PNGRB).
- Consumer Economics: Modest upfront OEM acquisition premium of ₹75,000 to ₹95,000 over conventional petrol variants; operating fuel cost of ₹2.80 to ₹3.40 per kilometre.
- Primary Strength: Instantaneous 5-to-7 minute refueling, complete freedom from range anxiety, and mature pan-Indian service capability.
2. Renewable Bio-CNG (Compressed Bio-Gas / CBG)
- Chemical Profile: $ge 90%$ biomethane purified to match strict Bureau of Indian Standards (BIS IS 16087:2016).
- Compatibility: 100% molecular drop-in replacement. Any CNG vehicle on the road today can burn 100% Bio-CNG or blended fuel without changing a single injector, pressure regulator, or spark plug.
- Sustainability Metric: Net carbon-negative. By capturing raw methane that would otherwise vent into the atmosphere from rotting agricultural parali or open cow-dung manure pits, Bio-CNG achieves a negative lifecycle carbon intensity score ($ -30 ext{ to } -80 ext{ gCO}_2 ext{eq/MJ}$).
- Regulatory Push: Mandatory 1% CBG blending into city gas networks in FY 2025–26, escalating to 5% by FY 2028–29.
3. Battery Electric Vehicles (BEVs)
- Energy Storage: Lithium Iron Phosphate (LFP) or Nickel Manganese Cobalt (NMC) battery packs ranging from 19 kWh (entry hatchbacks) to 60+ kWh (premium SUVs).
- Infrastructure Footprint: Approximately 12,500 public charging points nationwide according to NITI Aayog, heavily concentrated in Tier-1 metro highway corridors.
- Consumer Economics: High upfront capital expenditure—typically a ₹4.5 to ₹6.5 Lakh premium over equivalent petrol hatchbacks; low home-charging cost of ₹1.10 to ₹1.60 per km when domestic power is available, but rising to ₹4.50 to ₹6.00 per km at commercial DC fast-charging plazas.
- Primary Strength: Zero tailpipe emissions, instant electric torque, and lowest running cost for drivers with dedicated overnight residential charging sockets.
🏢 The Apartment Charging Chasm: Why 82% of Urban Buyers Can’t Plug In
In Western Europe and North America, early EV adoption flourished because a significant proportion of car owners live in suburban single-family homes with private garages or driveways. Plugging a vehicle into a 7 kW Level-2 wallbox overnight is effortless.
In urban India, the physical reality is fundamentally different:
- Multi-Story Apartment Complexes: Over 82% of passenger car buyers in cities like Mumbai, Bengaluru, Delhi-NCR, Pune, and Hyderabad reside in cooperative housing societies or high-rise apartment towers.
- Metered Power Constraints: Installing a dedicated 7 kW charging line from a 14th-floor residential electricity meter down to an open basement parking bay routinely triggers intense disputes with housing society Resident Welfare Associations (RWAs), requires complex electrical load enhancement approvals from state distribution companies (DISCOMs), and costs ₹45,000–₹80,000 in dedicated cabling alone.
- Street Parking Norms: In dense Tier-2 municipal wards, millions of vehicle owners park on public streets, pavements, or shared neighborhood lanes where overnight curbside EV charging is physically impossible.
For this vast majority of Indian motorists, an EV cannot be conveniently charged while they sleep. It requires either dedicated visits to commercial fast-charging plazas—sacrificing 45 to 90 minutes of personal time—or enduring perpetual battery anxiety.
A factory-fitted CNG vehicle, by contrast, requires zero residential electrical infrastructure. A driver visits a local CNG pump once a week for 6 minutes, refuels at ₹80–₹85/kg, and continues driving without modifying their apartment's electrical supply.
A granular breakdown of India's multi-fuel mobility future across 5 critical transport categories, grounded in SIAM, NITI Aayog, and PNGRB data.
82% lack dedicated home charging. Upfront CapEx delta is only ₹85,000 for CNG vs ₹5 Lakh for EV. 24-hour double-shift uptime. A 90-min daytime DC fast charge forfeits ₹600–₹800 in daily fares. Lightweight 3 kWh portable battery packs enable home charging for 2W, while 3W autos rely on high-pressure city CNG grids. Battery payload penalty: 400 kWh batteries weigh 3.8 tonnes, reducing revenue payload. Gas retains 100% hauling payload.
Who Rules Which Vehicle Segment by 2030? (CNG vs Bio-CNG vs EV)
Sub-₹10 Lakh Personal Commuters
Ola, Uber, Airport & Intercity Cabs
Daily Scooters & Auto Rickshaws
Long-Haul Trucks & Multi-Axle Trailers
🚕 Commercial Fleet Economics: The Strict 24-Hour Double-Shift Rule
Nowhere is the powertrain race more fiercely contested than in commercial transportation: app-cabs (Ola, Uber), intercity taxis, airport shuttles, and last-mile delivery vehicles.
In commercial fleet management, a vehicle is an asset that only generates revenue when its wheels are turning.
| Operational Parameter | Factory-Fitted CNG Fleet (e.g. Tour S / Tigor) | Commercial Battery EV Fleet (e.g. Xpres-T) | Economic Impact |
|---|---|---|---|
| Upfront Vehicle CapEx | ₹6.5 - ₹7.5 Lakh | ₹13.0 - ₹14.5 Lakh | ₹6.5 Lakh higher capital risk per cab |
| Daily Duty Cycle | 240 – 320 km (Double-Shift) | 160 – 210 km (Single-Shift limited) | 35% lower daily earning window for EV |
| Mid-Shift Downtime | 6 – 8 minutes at CNG dispenser | 60 – 90 minutes at DC fast charger | Forfeits 2 to 3 peak billing trips daily |
| Energy Cost / km | ₹2.80 - ₹3.20 / km | ₹2.10 - ₹2.60 / km (Commercial DC tariff) | Negligible operating difference at public plugs |
| Battery Replacement Cost | N/A (Engine overhaul: ₹35,000) | ₹4.2 - ₹5.5 Lakh after 180,000 km | Severe balance sheet hit in Year 3 or 4 |
| Clean Air Mandate Status | 100% Legal under CAQM GRAP-IV | 100% Legal under CAQM GRAP-IV | Both exempt from diesel bans |
As demonstrated by the matrix above, an app-cab driver operating on thin margins cannot afford to park beside a 50 kW DC fast charger for 75 minutes in the middle of a high-demand afternoon surge. That charging downtime directly translates to ₹600 to ₹800 in forfeited gross fare revenue every single day.
Furthermore, while domestic residential charging costs ₹1.20/km, commercial DC fast-charging operators charge ₹18 to ₹24 per kWh (including GST and parking fees), which inflates real EV fleet running costs to ₹2.40–₹2.80/km—virtually eliminating the running cost gap with CNG.
For commercial passenger fleets, CNG and Bio-CNG will retain more than 75% market share through 2030.
🚛 Heavy Commercial Transport: The 3.8-Tonne Battery Weight Penalty
When examining medium and heavy commercial freight (16-tonne haulers up to 55-tonne prime movers), the physical laws of chemistry and gravimetric energy density firmly favor gas molecules over lithium-ion batteries:
The Payload Math
- Diesel Energy Density: $approx 12,000 ext{ Wh/kg}$.
- Compressed Natural Gas Density: $approx 13,800 ext{ Wh/kg}$.
- Commercial LFP Battery Density: $approx 160 ext{ Wh/kg}$ (cell level) or $approx 110 ext{ Wh/kg}$ (pack level).
To power a 28-tonne commercial freight truck for a realistic 450 km intercity route between Delhi and Jaipur, an electric powertrain requires a massive 400 to 500 kWh battery pack.
- Weight of 450 kWh Battery Pack: Approximately 3,600 to 4,200 kg (3.8 tonnes) of dead weight.
- Weight of CNG/LNG Fuel System: Approximately 650 to 800 kg for high-pressure composite cylinders or cryogenic dewars providing equivalent range.
Under India’s strict MoRTH Gross Vehicle Weight (GVW) regulations, every kilogram of battery deadweight reduces the legally allowable cargo weight the truck operator can bill for. Carrying 3.8 tonnes of battery means losing up to 20% of paying freight on every single trip.
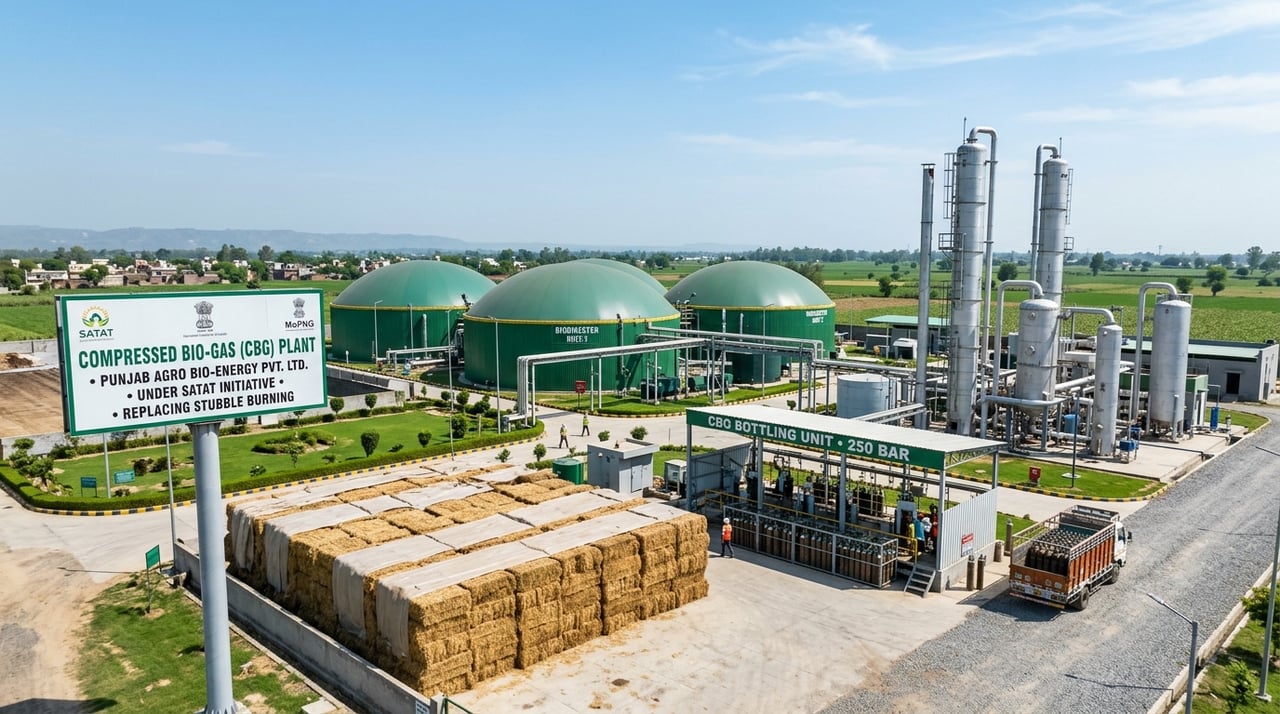
For this reason, commercial haulage operators across India are turning to Bio-CNG and Liquefied Natural Gas (LNG). With over 150 highway corridors being equipped with high-capacity cryogenic and fast-fill gas dispensers, long-haul freight in India is poised to decarbonize through biomethane, not multi-tonne battery packs.
🌍 The Lifecycle Carbon Audit: Tailpipe Zero vs. Well-to-Wheel Reality
One of the most persistent misconceptions in public discourse is that electric vehicles are automatically "zero emissions."
While an EV has zero tailpipe exhaust, its real-world environmental benefit depends entirely on the cleanliness of the electricity grid that charges its cells.
India’s Power Grid Reality (2025–2026)
According to the Central Electricity Authority (CEA), approximately 64% to 68% of India’s electrical generation is coal-fired. The average carbon intensity of the national grid remains around 710 to 740 gCO$_2$ per kWh.
When an electric vehicle is charged from a coal-dominated grid: $ ext{Lifecycle EV Emissions} = rac{14 ext{ kWh}}{100 ext{ km}} imes 725 ext{ gCO}_2/ ext{kWh} approx 101.5 ext{ gCO}_2/ ext{km}$
Compare this to the full well-to-wheel lifecycle footprint across all three fuels:
- Conventional Petrol Car: $approx 165 ext{ to } 185 ext{ gCO}_2/ ext{km}$
- Standard Fossil CNG Car: $approx 115 ext{ to } 130 ext{ gCO}_2/ ext{km}$ (25–30% reduction vs petrol)
- Coal-Grid Charged EV: $approx 98 ext{ to } 115 ext{ gCO}_2/ ext{km}$ (Comparable to efficient CNG)
- Renewable Bio-CNG Car: $approx -15 ext{ to } 35 ext{ gCO}_2/ ext{km}$ (Net-Negative to 80% lower than coal-powered EV)
Because Bio-CNG prevents raw agricultural stubble burning and captures organic waste methane, it delivers a substantially cleaner well-to-wheel climate score in today's India than charging an EV with coal power. As the grid greens through 2030, EVs will improve; but Bio-CNG already delivers negative-carbon mobility today.
🔮 The 2030 Verdict: India’s Pragmatic Tri-Fuel Equilibrium
The notion that one powertrain will completely exterminate the others by 2030 is contradicted by India's infrastructure investments, income demographics, and regulatory frameworks.
By 2030, India’s road transport will settle into a stable, highly logical three-fuel ecosystem:
- Electric Powertrains Will Dominate Two-Wheelers & Urban Compacts (30% Overall Share):
- Lightweight 2.5–3.5 kWh portable batteries can be detached and carried indoors for charging.
- Urban last-mile delivery two-wheelers and compact commuter scooters will be 60%+ electric.
- CNG & Bio-CNG Will Dominate Budget Cars, Fleets & Medium Freight (50% Overall Share):
- Sub-₹10 Lakh passenger cars, ride-hailing taxis, 3-wheeler auto-rickshaws, and regional delivery trucks will run predominantly on high-pressure gas.
- Blending mandates will see 5% to 10% renewable Bio-CNG circulating through national pipelines, progressively decarbonizing millions of existing vehicles without vehicle scrap mandates.
- High-Efficiency Hybrids & Residual Diesel Will Handle Long-Haul Heavy Transit (20% Share):
- Multi-axle long-distance interstate haulers and premium intercity passenger vehicles will utilize strong hybrids and LNG to overcome long-distance remote gaps.
India's path to green mobility is uniquely pragmatic: electrifying where weight is light and charging is easy; gasifying where load is heavy and continuous uptime is non-negotiable.
❓ Frequently Asked Questions (FAQ)
Can I fill Bio-CNG in my existing factory-fitted CNG car?
Yes, absolutely. Bio-CNG (CBG) is molecularly identical to compressed fossil natural gas, consisting of 90–96% pure methane ($CH_4$). It conforms to the identical BIS IS 16087 automotive fuel standard. You do not need any mechanical modifications, re-tuning, or special adapters—it blends seamlessly in the same fuel tank.
Why are EVs more expensive upfront than CNG cars in India?
An electric vehicle requires an imported lithium-ion battery pack, sophisticated liquid-cooling thermal management systems, high-voltage inverters, and drive controllers. For a typical passenger car, the battery alone costs ₹3.5 to ₹5.5 Lakh. A factory CNG system requires high-grade steel/composite cylinders, sequential gas injectors, and a pressure regulator, which costs vehicle manufacturers only ₹65,000 to ₹85,000 to integrate.
What happens to CNG stations when EVs expand by 2030?
CNG stations are not disappearing—they are expanding. Under PNGRB authorizations, the national network is growing from 8,340 pumps today to over 14,000 by 2030. Furthermore, major oil and gas marketing companies (IOCL, BPCL, HPCL, IGL, MGL) are converting conventional retail pumps into Integrated Energy Plazas that offer high-pressure CNG dispensers alongside ultra-fast DC EV charging bays.
How can I verify live CNG pump status and pressure before fueling?
You can use the CNGWALA Web & Mobile App to check live dispenser pressure (bar), estimated queue lengths, and verified community operational reports across 7,000+ stations nationwide in real time.
Research Methodology & Regulatory Citations
All macroeconomic projections, vehicle registration statistics, and fuel policy targets referenced in this analysis are cross-referenced with primary publications from the Ministry of Petroleum and Natural Gas (MoPNG), the Petroleum and Natural Gas Regulatory Board (PNGRB), the Society of Indian Automobile Manufacturers (SIAM), the Central Electricity Authority (CEA), and NITI Aayog.
Live station data, operating pressure benchmarks, and queue tracking algorithms are maintained by the CNGWALA Intelligence Platform.
Official Data Sources & Regulatory Citations
All figures in this analysis are cross-referenced with primary Indian energy bodies.
Cite & Reference This Analysis
Free to reference in research papers, industry reports, news articles, and commercial blogs.
CNGWALA Mobility Intelligence Team (2025). "CNG vs Bio-CNG vs EV: India’s 2030 Green Mobility Race Decoded". CNGWALA Mobility Intelligence. Retrieved from https://www.cngwala.com/blog/cng-vs-bio-cng-vs-ev-which-will-rule-india-s-green-mobility-race-by-2030
[CNG vs Bio-CNG vs EV: India’s 2030 Green Mobility Race Decoded — CNGWALA Mobility Report](https://www.cngwala.com/blog/cng-vs-bio-cng-vs-ev-which-will-rule-india-s-green-mobility-race-by-2030)